CCS in Europe and the NZIA
A practitioner’s briefing from Max Richards, Head of CCUS Studies at OPC
A note from Max
Welcome to the first issue. I lead CCUS studies at OPC, where our geoscience and engineering team works across the whole CCS chain: storage screening, site characterisation, development, injection, and technical due diligence for lenders and investors. This briefing is written from that perspective, as my take on what recent developments mean for anyone who needs, builds or finances CO2 storage in the EU, Norway and the UK.
Issue 1 sets a baseline for a generalist audience – where CO2 storage in Europe stands today. This first issue focuses on the obligation in Article 23 of the EU Net-Zero Industry Act (NZIA): what it requires, how much EU capacity is likely by 2030, where the stores are, the legal position and what is driving demand, plus my takeaways from CCUS 2026, the Carbon Capture and Storage Association's UK conference in October. Later issues will widen the focus to other parts of the CCS chain. From November, updates will be shorter, focusing on what has changed, what it means and what to watch next month.
Max Richards
Head of CCUS Studies, OPC
1. The Obligation
- Article 20 of the NZIA (Regulation (EU) 2024/1735) sets an EU objective of at least 50 million tonnes per year (Mtpa) of CO2 injection capacity by 2030. Article 23 divides that objective between EU oil and gas producers.
- Each producer's share is in proportion to its share of EU oil and gas production from 2020 to 2023. Commission Decision (EU) 2025/1479 names the 44 companies concerned (the obligated entities) and their individual shares. This briefing does not comment on individual companies' obligations.
- Only injection capacity at storage sites in the EU, including its offshore economic zones and continental shelf, that are permitted under the CCS Directive (2009/31/EC) counts, and it must be available to the market by 2030. Storage in the UK and Norway does not count under the law as it stands, and nor does storage combined with enhanced oil or gas recovery.
- To comply, obligated entities need to show qualifying permitted injection capacity available to the market by the end of 2030, at sites designed to operate for at least five years with fair and open access. They can develop storage themselves, agree with other obligated entities, or contract with third-party storage developers or investors. A final investment decision (FID) shows progress but is not compliance. A storage agreement with an emitter may help show that capacity is available to the market, but the Regulation does not define it as a means of compliance.
- The Commission published its first progress report in May 2026; the next is due by 30 June 2027.
Sources: Regulation (EU) 2024/1735 Arts. 20 and 23; Decision (EU) 2025/1479; COM(2026) 252; Article 23 Watch FAQ.
2. The Capacity Gap
EU CO2 injection capacity by 2030 (Mtpa)
The Commission's first progress report (May 2026) lists three EU sites holding a storage permit under the CCS Directive: Porthos (Rotterdam), Greensand (Danish North Sea) and Prinos (northern Greece), with about 3.5 Mtpa between them. A further 15.6 Mtpa was going through permitting. Since then, all three Aramis stores in the Netherlands have been permitted (Shell's K14-FA/FC in May, TotalEnergies' L04-A in July and Eni's L10-ALBE on 30 September), so six EU sites now hold permits. The Aramis partners still plan to start in 2030, but the Dutch government expects 2031, after a final investment decision in 2027.
Member States' own reports add up to 33 Mtpa by 2030. In March 2026, Article 23 Watch, which tracks the obligation, estimated 43 Mtpa from announced projects, with 50 Mtpa reached closer to 2032. In June 2026, IOGP Europe reported that ten announced projects had since been cancelled or postponed, cutting announced EU capacity by 2030 to about 35 Mtpa. Only 2.9 Mtpa had reached a final investment decision. Wood Mackenzie expects the EU to fall at least 17.5 Mtpa, about 35%, short of the objective, even if every project in advanced development goes ahead.
Not everyone is as pessimistic: the Global CCS Institute's Head of Europe still calls 50 Mtpa achievable, pointing out that Europe has 13% of the world's operational CCS projects and more than a third of the global pipeline under construction. Permitted capacity is small compared with the objective at the time of writing and, from the perspective of obligated entities, much of the storage capacity coming online soon is already taken by owners' own obligations or regional emitters.
Reality check: what is actually stored
- The Global CCS Institute's Global Status of CCS 2026 counts over 100 operational CCS projects worldwide. The amount of CO2 they store is much smaller than that number suggests.
- The London Register of Subsurface CO2 Storage (LRSCS; Imperial College London, 2026) records 43.6 Mt of CO2 stored worldwide in 2024, across 49 projects in 13 countries.
- 83% of that came from projects with oil recovery. Dedicated geological storage was 7.4 Mt worldwide, less than a sixth of the EU's 2030 objective.
- In the EU, the only dedicated geological storage reported (in the LRSCS) for 2025 was 0.03 Mt at Ravenna Phase 1. The other EU volumes, in Croatia and Hungary, came from CO2-EOR, where CO2 is injected to boost oil recovery. Storage combined with enhanced oil or gas recovery does not count towards the NZIA objective.
- About a third of all CO2 recorded as stored was reported against no published standard. Independently verified storage matters as Article 23 compliance is tested against the EU CCS Directive.
Sources: COM(2026) 252 (28 May 2026); Article 23 Watch annual report (Mar 2026); IOGP Europe (9 Jun 2026); Wood Mackenzie (17 Jun 2026); Global CCS Institute opinion, Carbon Herald (29 Oct 2026); Industrylinqs (16 Oct 2026, Aramis permits); Regulation (EU) 2024/1735 Art. 20; CATF storage tracker (Jun 2026); Gao, Elizarev and Krevor, The London Register of Subsurface CO2 Storage: 2026 Annual Report, Imperial College London; Global CCS Institute, Global Status of CCS 2026.
3. Legal and Enforcement
- Twelve obligated entities filed fifteen cases at the EU General Court in October 2025, challenging the Commission decision that sets their shares of the obligation, and the principle of the obligation under the NZIA. The cases are pending and do not suspend the obligation.
- In August 2026 ExxonMobil gave notice of an arbitration claim over the obligation under the Energy Charter Treaty, an international investment-protection treaty. A cooling-off period must pass before arbitration can begin.
- Member States were due to set penalties for non-compliance by June 2026. Germany indicates c.130 to 145 EUR/t; most others have no compliant regime.
Sources: General Court register (T-711/25 and others); Article 23 Watch (Mar, Sep 2026); Bellona Member State tracker (Dec 2025). OPC view is professional judgement, not legal advice.
4. The Storage Landscape
EU stores (count under Article 23)
| Store | Status | Capacity (Mtpa) | 2030 availability |
|---|---|---|---|
| Greensand (DK; INEOS, Harbour, Nordsøfonden) | Operating since Sep 2026 | 0.4 now; 4 to 8 potential | Expansion phases only |
| Porthos (NL; EBN, Gasunie, Port of Rotterdam) | Construction; start H2 2027 | c.2.5 | Storage fully allocated |
| Aramis (NL; Gasunie, EBN, Shell, TotalEnergies) | All three stores permitted (May to Sep 2026); FID planned 2027; start 2030 (partners) or 2031 (Dutch government) | Up to 5 (launch stores); 5 at Eni's L10 store | Uncertain |
| Ravenna (IT; Eni, Snam) | Phase 2 in permitting; start by 2030 | 4 by 2030; up to 16 | Expected to be open to third parties |
| Prinos (GR; EnEarth, Energean group) | Permitted; under construction | 1 (Phase 1); up to 2.8 | Limited |
| Bifrost (DK; TotalEnergies-led) | Seabed surveys of the Inez site completed Oct 2026 | Up to 9 from 2034 (Inez and TotalEnergies' Dagny site: up to 335 Mt combined) | After 2030 |
| Norne (DK; Norne CCS) | Early stage | 15+ (2030s) | After 2030 |
Non-EU stores (do not count as drafted)
| Store | Status | Capacity (Mtpa) | Note |
|---|---|---|---|
| Northern Lights (NO; Equinor, Shell, TotalEnergies) | Operating since Aug 2025 | 1.5; 5+ by 2028 | Capacity available now |
| Atlas (NO; Aker BP, ORLEN) | EUR 223m Innovation Fund award | 6 from 2031 | ORLEN, a Polish obligated entity, holds 20% |
| Smeaheia (NO; Equinor) | Appraisal | Up to 20 (2030s) | Pipeline and ship options |
| Endurance (UK; bp, Equinor, TotalEnergies) | Construction; pipelay vessel arrived Sep 2026 | 4 from 2028 | Teesside; UK government-backed |
| Liverpool Bay (UK; Eni) | Construction; start Q4 2028 | 4.5; up to 10 | HyNet cluster, East Irish Sea |
| Morecambe Net Zero (UK; Spirit Energy) | Development | c.4 | East Irish Sea; 2030 target |
| Hewett (UK; Eni) | Appraisal well announced by the NSTA, Oct 2025 | Up to 10 (early 2030s) | Depleted gas field, Southern North Sea; landfall at Bacton |
| Poseidon (UK; Perenco, Carbon Catalyst, Harbour) | UK's first CO2 injection test completed at Leman, Apr 2025 | Not yet confirmed | Depleted Leman gas field, Southern North Sea |
Should storage outside the EU count?
The NZIA only counts injection capacity at storage sites in the EU that hold a permit under the CCS Directive, so stores in Norway and the UK are excluded. Yet the only open-access store reporting spare capacity today is Norway's Northern Lights, and the UK's two leading stores, Endurance and Liverpool Bay, are under construction.
- IOGP Europe, the association of oil and gas producers in Europe, proposed in June 2026 that storage in the EEA (which includes Norway) and the UK should count.
- ORLEN, a Polish company with its own Article 23 share, holds 20% of Atlas, a Norwegian store. Obligated entities are already investing on the other side of the line.
- Belgium has called for the UK to be included in the EU's CO2 transport and markets rules, due from the Commission in Q1 2027.
- Industry pressed the same point at CCUS 2026, even though NZIA was not on the agenda in its own right.
When could non-EU storage come online?
OPC estimate of announced injection capacity, from operators' published capacities and start dates, with Norway and the UK added on top of the EU stores profiled in this briefing.
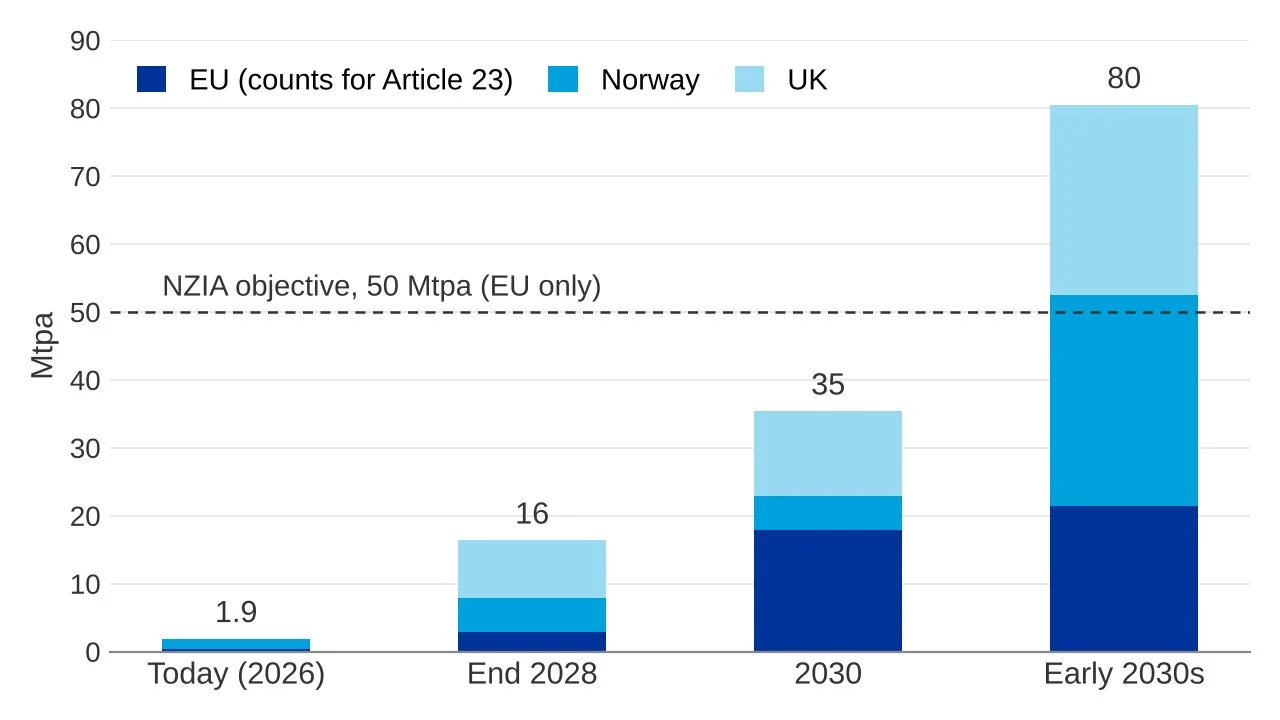
Adding Norway and the UK would take total announced capacity past 50 Mtpa in the early 2030s. Start dates tend to slip, though, much of the UK capacity is committed to emitters in its own clusters (Teesside and the Humber for Endurance, HyNet for Liverpool Bay), and Northern Lights already has seven customers. The capacity that could actually be offered to EU obligated entities before 2030 is a fraction of these totals.
The ETS is a separate question. The Global CCS Institute suggests the current EU ETS review could exempt CO2 permanently stored in non-EU countries with a linked ETS from allowance surrender. That would matter most for UK stores if the UK and EU schemes are linked, but it would not change what counts towards the NZIA objective.
Our view: we think whether storage outside the EU will count is the biggest unknown in the market, but a change in the rules would not settle it. Counting Norwegian and UK storage would not by itself make that capacity commercially available to obligated entities, and because the objective is to develop capacity inside the EU, it might not remove the obligation either. If non-EU storage were counted, it could ease the 2030 gap. If not, permitted EU capacity will sell at a premium. We haven't yet seen anyone price either outcome openly.
Chart basis and underlying data
Chart basis. EU: Greensand, Porthos, Aramis (including Eni's L10; counted at the partners' 2030 date, although the Dutch government expects 2031), Ravenna Phase 2, Prinos and, in the early 2030s, Greensand expansion at the low end; smaller EU projects are excluded, so this sits below IOGP Europe's 35 Mtpa of announced EU capacity. Norway: Northern Lights, Atlas, Smeaheia. UK: Endurance, Liverpool Bay, Morecambe Net Zero, Hewett. Early 2030s figures use upper-end announced capacities. Sign up to get the underlying data (Excel), sent by email.
The Net-Zero Industry Act NOT the Deindustrialise and Offshore Act
On the one hand, a tonne stored in Norway or the UK does as much for the climate as a tonne stored in the Netherlands, and it's often available sooner. On the other, this is the Net-Zero Industry Act, not the Deindustrialise and Offshore Act. Its stated aim is a Union market for CO2 storage services, not sending Europe's storage industry, and the jobs and supply chain that come with it, to Norway and the UK. So is Article 23 about industrialisation or emissions? The text says industrialisation. The ETS already looks after emissions. How the Commission settles that in its 2027 review is the question I'd watch.
UK stores. The UK Autumn Budget prioritises CCUS projects in Teesside, Merseyside and North Wales, and keeps grant funding for Viking CCS in the Humber, but saves GBP 200m from CCUS capital grants. That leaves Acorn in north-east Scotland without confirmed grant funding; future government support moves to loans and equity. Separately, the Northern Endurance Partnership (bp, Equinor and TotalEnergies) has completed a two-well appraisal of two potential stores on its CS006 and CS007 licences, alongside Endurance. It plans FEED for this expansion in 2027 and FID in 2028; Endurance itself remains on track to start in 2028. Indicative heads of terms have also been published for Transition Access Agreements, under which projects pay all transport and storage charges up to an agreed per-tonne threshold.
Sources: operator announcements (INEOS, Porthos, Aramis, Eni, Snam, EnEarth, Northern Lights, Aker BP, Equinor, NEP, Spirit Energy, Perenco), Apr 2025 to Oct 2026; COM(2026) 252; CATF tracker; IOGP Europe (Jun 2026); CCSA weekly newsletters (23 and 30 Oct 2026); Carbon Capture Journal (26 and 30 Oct 2026); Carbon Herald (30 Oct 2026, Acorn); OPC notes, CCUS 2026. Non-EU capacity timeline is an OPC estimate from announced figures.
5. Demand and Funding
Sweden pays only for stored CO2. The Swedish Energy Agency has awarded SEK 9.3 billion (c.EUR 840m) by reverse auction to three waste-to-energy operators to capture and store 5.75 Mt of biogenic CO2, the CO2 released from burning the biomass share of waste. Storage must start within four years and payment is made only once CO2 is stored. Including Stockholm Exergi's project, c.17 Mt is expected to be stored by 2046.
| Operator | Award | CO2 stored |
|---|---|---|
| SYSAV (SkyZero, Malmö) | SEK 6.3bn | 3.6 Mt |
| Renova | SEK 1.6bn | 0.89 Mt |
| Öresundskraft | SEK 1.4bn | 1.26 Mt |
- Sweden has no storage of its own, so this is new demand for North Sea capacity, much of it outside the EU. Öresundskraft has already contracted with Northern Lights.
- Yara's carbon capture plant at Sluiskil in the Netherlands, inaugurated in September, will capture about 800,000 tonnes a year for shipping to Northern Lights.
- EU Innovation Fund, the grant programme funded by Emissions Trading System revenues: the 2025 round (announced 20 October) awards EUR 3.4bn to 77 projects and was oversubscribed in every category. Ravenna Phase 2 selected; Atlas awarded EUR 223m, conditional on FID in 2028.
- EU Emissions Trading System (ETS) review (COM(2026) 616, July): the Commission proposes using 250 million allowances in 2031 to 2040 to buy permanent carbon removals within the EU. Negotiations between Parliament, Council and Commission are targeted for Q1 2027.
- Austria: CO2 storage is currently banned. A draft CO2 Storage Act would lift the ban; consultation closed on 30 October. OMV, Austria's largest oil and gas company, has an Article 23 share of 0.96 Mtpa.
Sources: Carbon Credits (LinkedIn, 23 Oct 2026), reporting the Swedish Energy Agency award; Northern Lights (1 Oct 2026); JPT (13 Sep 2026, Yara Sluiskil); Eni (20 Oct 2026); Aker BP (20 Oct 2026); Bellona (Oct 2026); COM(2026) 616; Carbon Herald (Austria).
6. From the Floor: CCUS 2026
CCUS 2026 is the Carbon Capture and Storage Association's UK conference, held at Central Hall Westminster, London, on 13 and 14 October. It brings together project developers, emitters, government, lenders and insurers. I attended both days. What stood out:
- Storage is operating commercially, but spare capacity for third parties is thin. Early capacity at the first EU stores is largely spoken for, and new third-party capacity depends on expansion phases and new hubs.
- The finance community sees capital as available and geological risk as acceptable to some banks. Revenue certainty, utilisation and cross-chain risk allocation decide bankability.
- How an asset is held and financed, for example the split between debt and equity, can move storage cost by around 20 EUR/t: roughly 50 against 70 EUR/t.
- The hardest risk to insure is business interruption without physical damage: when injection stops or slows, revenue stops.
- The UK and continental markets are moving from state-backed first projects towards aggregators, which collect CO2 from many smaller emitters and contract transport and storage on their behalf. A fully commercial market without state support is expected in 10 to 15 years (don't hold me to this).
- Norway is positioning itself as Europe's storage provider, pointing to the Northern Lights expansion from 1.5 to 5 Mtpa and 10 storage exploration licences. Norway's Minister of Trade and Industry set this out in a keynote.
- NZIA was not on the agenda in its own right, but industry pressure for UK and Norwegian stores to count is growing.
Source: OPC notes, CCUS 2026. Themes summarised across sessions; only public keynote remarks are attributed.
7. So What? What This Means for the Market
- Permitted EU capacity for 2030 sits in a handful of stores, and several of those are already taken by owners' own obligations or regional emitters.
- Obligated entities without their own storage are likely to need contracted access to permitted capacity available to the market by 2030. An FID or an agreement with an emitter does not meet the obligation on its own.
- Pay-on-storage schemes such as Sweden's add demand for North Sea capacity, much of it outside the EU.
OPC view is professional judgement, not legal advice.
Working on any of this?
OPC's subsurface and engineering team supports storage screening, site characterisation, injection design, monitoring and technical due diligence for developers, emitters and investors. If you are weighing up storage options or an Article 23 position, I would be glad to talk it through.
Email Max8. What to Watch in November
| When | Item | Why it matters |
|---|---|---|
| From 30 Oct | Next steps on Austria's CO2 Storage Act after consultation closed on 30 Oct | Could open onshore storage in Central Europe |
| Late Oct to Nov | Cooling-off period on ExxonMobil's Energy Charter Treaty notice ends | Arbitration over Article 23 could proceed |
| 9 to 21 Nov | COP31, the UN climate conference, Antalya | Article 6 rules on international carbon credit trading |
| Ongoing | Industrial Accelerator Act proposals to favour lower-emission goods in public procurement (per the Global CCS Institute) | Could create paying demand for low-carbon cement and steel |
| Dec | Next EU Innovation Fund calls open | Further grant funding for capture and storage |
| 2 Dec | CCS4G, the GESGB symposium on CCS for geoscientists, Geological Society, London | Regulation, liability, cross-border storage |
| 3 Dec | European Industrial Carbon Management Summit, Brussels | EU industrial carbon management policy |
Dates are as published by the organisers or sources cited; the end of the cooling-off period is expected rather than confirmed.
References (32): click to expand
About the author
Max Richards is Head of CCUS Studies at OPC in London and a CCS integration specialist. He also chairs the SPE London Net Zero Committee. OPC are subsurface and engineering specialists. OPC's CCS practice covers the whole value chain, from regional storage screening and site characterisation to pilot injection design, operational monitoring and technical due diligence, for clients internationally.
If you are working on any of this and would like to talk, write to [email protected].